BoG Proposes 30-Day Liquidity Rule for Banks
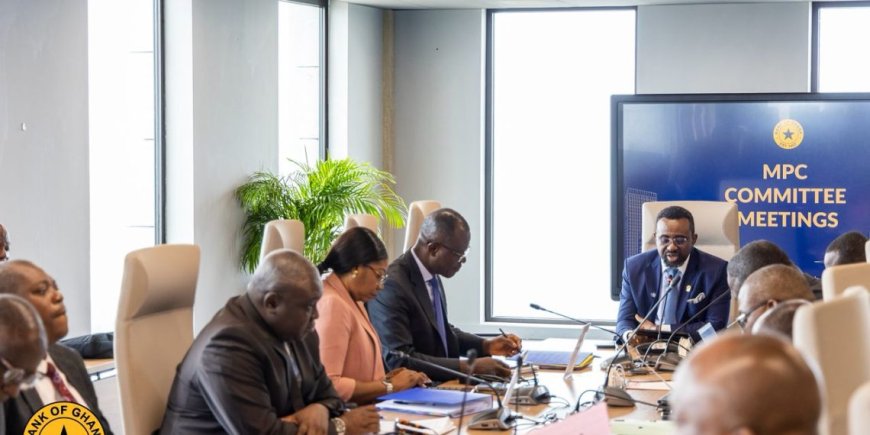
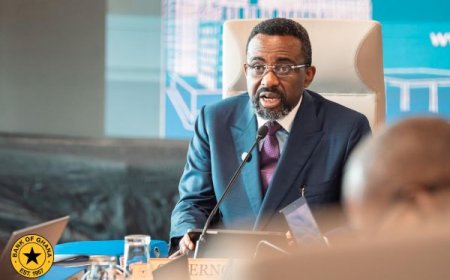
The Bank of Ghana (BoG) is preparing to introduce a Liquidity Coverage Ratio (LCR) requirement for banks as part of efforts to strengthen liquidity risk management and improve their ability to withstand financial shocks.
The central bank has invited the banking industry and the general public to submit comments on the proposed Liquidity Coverage Ratio Directive before it is finalised.
The consultation is being conducted in line with the BoG’s Procedures for Issuance of Directives, 2020.
Under the proposed framework, banks would be required to maintain adequate high-quality liquid assets to meet their liquidity needs during a period of significant financial stress lasting 30 calendar days.
The requirement is intended to strengthen banks’ capacity to meet short-term obligations during periods of funding pressure.
It would also introduce a prudential benchmark for assessing banks’ liquidity buffers and their resilience to sudden cash outflows.
The directive forms part of broader efforts to strengthen the banking sector’s risk management framework.
The BoG has set November 30, 2026, as the deadline for submissions. Comments should be sent by email to bsdletters@bog.gov.gh.
The central bank says it will consider all material comments received and provide written explanations on how they were addressed, including whether they were incorporated into the final directive.
The consultation gives banks and other stakeholders an opportunity to raise implementation concerns and propose adjustments before the rules take effect.
The proposed liquidity rules come amid broader regulatory efforts to strengthen banks’ risk management practices.
The BoG has also outlined a Credit Risk Management Directive, which would complement the Non-Performing Loan Notice issued last year.
The credit-risk framework is expected to cover the full lending process, including credit origination, administration, monitoring, measurement and recovery.
While the credit-risk measures focus on how banks assess and manage lending risks, the liquidity coverage ratio requirement targets their ability to meet short-term financial obligations during periods of stress.
Together, the measures would address two important areas of banking-sector resilience: the quality of banks’ credit portfolios and their capacity to maintain sufficient liquid assets.
However, the proposed LCR requirement could have implications for treasury operations, liquidity planning and the composition of assets held to meet regulatory requirements.
The actual impact will depend on the final directive and the requirements adopted by the central bank.
Click the link Puretvonline.com | WhatsApp Channel to join the WhatsApp channel
Contact/WhatsApp: +233243201960 or manuelnkansah33@gmail.com